We'll help you buy the right Park Slope Co-ownership by avoiding costly structural issues, hidden repair expenses, and overpaying in a competitive market
Smooth transaction with limited risk
No pressure to over pay and buy within a certain time period
A team of people that will be with you even after the transaction is complete
Live listing data provided by OLR IDX. Need help? Contact us or log in to your customer account.
Co-ownership in Park Slope starts with one question: does this property actually work for multiple buyers? Not every brownstone, condo, or co op that fits a combined budget supports shared ownership well. The layout may lack privacy. The building's reserve fund may be nearly empty. The board may reject applications from unrelated co-buyers. A Park Slope co-ownership realtor evaluates these factors before you make an offer, not after.
Licensed Associate Real Estate Broker with SERHANT, in real estate since 2017, including co-ownership transactions
Completed 100+ career transactions, including shared-ownership properties
Average response time within 24 hours for co-ownership consultations
Track record helping co-buyers navigate brownstone, condo, and co op purchases together
Choosing the best real estate agent for a co-ownership purchase depends on experience and results with multi-buyer transactions. A conventional agent handles a single buyer or seller. A co-ownership real estate agent in Park Slope manages the added complexity of aligning multiple buyers' finances, preferences, and long-term goals around one property.
Stanley Montfort's practice is built around this difference. When evaluating a Park Slope property for shared ownership, I assess the building's physical condition, financial health, and governance rules alongside whether the unit layout, outdoor space, and carrying costs actually support the intended arrangement.
Property suitability analysis for multiple owners. Not every home that fits a combined budget works for co-ownership. I evaluate floor plans for privacy, separate entrances, soundproofing quality, and how shared versus private spaces are configured.
Local housing stock knowledge. Park Slope is known for its historic brownstones and tree-lined streets, but its housing stock varies from prewar co ops along Prospect Park West to modern condos near Fourth Avenue. Each property type carries different implications for shared ownership.
Financing and ownership structure planning. Before we start looking at properties, I connect co-buyers with lenders experienced in multi-borrower applications and attorneys who structure ownership agreements, whether the group is considering tenancy in common, an LLC, or another arrangement.
Due diligence protecting all co-owners' interests. I review building financials, reserve fund balances, special assessment history, and infrastructure condition reports so that co-buyers understand the real carrying costs before committing.
Co-ownership in Park Slope usually means buying a multi-family home with others, though the strategy applies to condos, co ops, and converted brownstones as well. Co-buying typically involves legal agreements detailing exit strategies and cost-sharing, but the real estate decision comes first: is this property physically, financially, and structurally suited for multiple owners?
I evaluate each property against co-ownership criteria, including unit configuration, building financial health, board or association rules, and current market pricing. With 217 homes currently for sale in Park Slope, the inventory spans a range of property types, but only a subset of those listings will support shared ownership well.
One of the first conversations I have with co-buyers covers how they plan to use the property, how long they expect to hold it, and what happens if one person needs to exit. These answers shape the entire search.
Townhouses are highly sought-after in Park Slope. Multi-family brownstone conversions, typically 3 to 8 units per building, offer co-buyers the chance to own in a neighborhood where single-buyer entry prices can exceed $6 million for multi-family townhouses.
Park Slope has many prewar and historic apartment buildings, and brownstone conversions carry specific risks. In a 4-unit brownstone, a $120,000 roof replacement means $30,000 per owner. Many small brownstone condos operate with minimal or no reserve funds, so large expenses arrive as special assessments without warning.
What I evaluate for co-ownership suitability in brownstones:
Layout and privacy. Do units occupy separate floors? Are there independent entrances? Interior walls in older conversions can be thin; I check for soundproofing between units.
Outdoor space allocation. Garden-level units, roof terraces, and shared yards require clear maintenance and use agreements. Differences in outdoor access affect ownership percentages and unit pricing.
Historic district compliance. Exteriors in landmark-protected areas are regulated. Facade changes require Landmarks Preservation Commission approval, adding time and cost to renovations.
Infrastructure age. Original plumbing, electrical systems, and cast-iron pipes in buildings from the 1920s through 1940s may need replacement within a few years of purchase. I flag these during property evaluation so co-buyers can factor the costs into their offer.
Condominiums in Park Slope are popular for modern living, with the average price of a condo in Park Slope at $1,070,000. Condos allow owners to hold title to a specific unit plus shared ownership of common spaces. Association rules tend to be less restrictive than co op board policies regarding sublets, alterations, and resale.
Co ops are available throughout Park Slope, reflecting the ownership type's market significance. Park Slope has numerous co op listings across the neighborhood. Buying into a co op means you do not own real estate directly; you purchase shares in a corporation that owns the building, plus a proprietary lease for your unit.
Park Slope co ops enforce strict guidelines regarding subletting and renovations. Co op boards require exhaustive financial disclosures for approvals, and co op boards generally demand a down payment of 20% to 25%. A local expert can help identify co op boards with lenient rules regarding multiple co-buyers on a single application.
One mistake I frequently see co-buyers make: assuming that any co op will accept an application from unrelated purchasers. Some boards reject multi-buyer arrangements outright. I research board policies before scheduling a showing, saving the group time and application fees.
Monthly maintenance fees in co ops can increase incrementally over time. Co op carrying costs cover building-wide expenses including mortgage and property taxes. Prospective buyers need to consider building financial health and maintenance fees as part of the total ownership cost, not just the purchase price.
| Factor | Co-op | Condo | Brownstone Conversion |
|---|---|---|---|
| Ownership Structure | Shares in a corporation + proprietary lease | Title to individual unit + shared common elements | Title to individual unit in a small converted building |
| Board / Association Approval | Required; often strict | Usually less restrictive | Varies; often self-managed |
| Typical Down Payment | 20–25% often required by the board | 10–20% typical | Varies by lender and building |
| Sublet Flexibility | Often restricted | Generally more flexible | Depends on condo documents and building rules |
| Reserve Fund Risk | Larger buildings typically have stronger reserves | Varies by building | Greater risk of underfunded reserves in small buildings |
| Entry Price per Sq. Ft. | Generally lower than comparable condos | Generally higher than comparable co-ops | Varies significantly by condition and location |
Selling a home begins with understanding today's market, and co-owned properties add layers to that analysis. When multiple owners must coordinate on timing, pricing, and showings, the sale process takes longer and requires more planning.
The market often discounts properties with unusual ownership structures. If one co-owner wants to sell while others do not, the available options depend on the legal framework established at purchase. Buyout provisions, valuation methods, and dispute resolution should be defined before purchase, not negotiated under pressure.
Home pricing depends on location, size, and condition, but for co-owned properties, the building's governance and financial history also affect what buyers will pay. A brownstone condo with a history of special assessments and no reserve fund will sell at a discount compared to a similar unit in a building with stable finances. Comparable sales in similarly structured buildings need to be used carefully; I pull comps from the same building type, unit configuration, and ownership structure to give co-sellers an accurate picture.
Before we start looking at properties, I meet with the full group of co-buyers. The goals of this first session:
Assess each buyer's financial readiness, including income, credit, savings, and risk tolerance
Discuss property type preferences: brownstone, condo, or co op, and the trade-offs of each
Clarify how the group plans to use the property, whether as a primary residence, investment, or combination
Provide referrals to attorneys experienced in co-ownership agreements and lenders who handle multi-borrower applications
One question every group should discuss before making an offer: what happens if one person needs to exit in two years? The answer shapes the ownership structure, the property type, and the buildings I recommend.
I filter available inventory against co-ownership criteria. In a market where inventory remains low and well-priced brownstones attract over 75 groups of buyers at open houses, targeted search matters.
For each property, I evaluate:
fFloor plan suitability for the number of co-owners (bedrooms, bathrooms, separate living areas)
Building financial statements, reserve fund balance, and recent capital expenditures
Infrastructure condition: roof age, facade compliance with Local Law 11 for taller buildings, plumbing, electrical, and waterproofing
Board or association rules regarding multiple owners, sublets, and alterations
Monthly carrying costs and how they would be allocated among co-buyers
Coordinating an offer from multiple buyers requires clear representation. I present a unified offer on behalf of the group, handle negotiations on price and terms, and manage the transaction through closing.
Negotiations are a key part of the process. In the current market, mortgage rates have stabilized near 6.25% after peaking above 7% in late 2024. That affects carrying cost projections and borrowing capacity for co-buyers. Co ops currently offer more room for negotiation than condos, which can benefit groups willing to navigate the board approval process.
Marketing strategies should highlight unique property features when co-owners eventually sell. I build resale considerations into the purchase strategy from day one.
Every co-ownership purchase is structured around the group and the property. A few illustrative examples:
For example, two families might buy a brownstone conversion in South Slope with separate entrances on each floor, and I would check the roof and major systems first to estimate near-term capital costs.
For example, three investors might buy a multi-unit property near Seventh Avenue with a resale plan built around selling units one at a time over several years.
For example, two friends might buy a two-unit condo in a prewar building off Prospect Park West, after board research confirms the association allows co-purchasing and has a funded reserve.
Each scenario starts with the same foundation: evaluating whether the property, building, and legal structure support the group's goals before committing.
Park Slope's neighborhoods vary in housing stock, price, and property type. Co-ownership opportunities exist across:
Prospect Park West and Berkeley Place: Prewar buildings with architectural detail, larger units, and proximity to Prospect Park. Many co ops in this area have established boards.
Family-focused blocks near the park and local playgrounds: Brownstone-lined streets between Fifth and Seventh Avenues with strong resale demand.
Transit-accessible corridors near F, G, and R subway lines: Properties near Fourth Avenue and Atlantic Terminal offer condo inventory with modern construction and easier board approval for co-buyers.
Mixed-use areas along Fifth and Seventh Avenues: A combination of residential and retail, with smaller buildings and brownstone conversions that can work for investment-focused co-ownership.
Demand extends to adjacent areas. Buyers looking for lower entry prices sometimes reach into South Slope or Gowanus while maintaining access to Park Slope schools and amenities.
Properties with clear physical separation between living spaces produce the best co-ownership outcomes. Brownstone conversions with units on separate floors and independent entrances reduce friction. Condos in buildings with funded reserves and flexible association rules offer more resale options. Co ops can work if the board accepts multi-buyer applications, though Park Slope co ops enforce strict guidelines that require advance research.
The right property depends on the group. Two families sharing a four-bedroom brownstone need a different layout than three investors splitting a multi-unit building. I evaluate each listing against the group's specific use case.
When multiple buyers apply for a joint mortgage, lenders generally evaluate the credit, income, debt-to-income ratio, and financial position of each borrower. Down payment and closing-cost contributions should align with the intended ownership structure and be documented in a co-ownership agreement prepared by an attorney.

 Posted on Google
Stanley Montfort represented me in the sale of my home in Hamilton Heights. He is professional in his approach and brings his warm, personable demeanor into all his interactions. I selected Stanley to represent me after doing a thorough analysis of realtors in the Hamilton Heights area looking at number of closed tra…
 Posted on Google
Stanley was great to work with. He worked with our schedule, took the time to understand our priorities, showed us a range of properties in different areas that could suit our needs and helped us strategize our approach. He was also a great resource in helping us find local connections for inspections, repairs, etc.…
 Posted on Google
Thank you for a streamlined process from start to finish ensuring the right place was found and secured without haste!
 Posted on Google
We had a great experience working with Stanley. He taught us a lot about the specific market we were looking in, which enabled us to make a very good decision on purchase of a new home.
 Posted on Google
Stanley was the dream real estate agent we didn’t know we deserved! From the beginning he was attentive to our curiosity to help us figure out what type of property we wanted - and could afford. Throughout the process he was a calm and patient presence in our lives, offering us sincere and sage perspectives to keep u…
 Posted on Google
Stanley is amazing! No one knows the Harlem market better than him, and his deep expertise was a tremendous resource. He taught me along the way how to spot 'red flags' and talked me out of making an offer on a place that seemed amazing but had, upon his close inspection, evidence of poor workmanship and lots of cut co…
 Posted on Google
Stan is extremely knowledgeable and professional. He also has the utmost patience! He helped me sell my home and purchase a condo at the same time. My home had all types of special contingencies but he was able to find me a buyer and get me very close to the price I wanted. I was very specific in terms of the property…
 Posted on Google
Stanley is the consummate professional! He made sure my listing has excellent and consistent foot traffic and quality candidates for our showings. This sale had some challenges, but Stanley never wavered. Ultimately we were successful and I’ll use him again and again for future real estate transactions.
Practical guides from Stanley Montfort on buying, selling, and pricing NYC homes.
How to structure a co-ownership purchase and what the agreement should cover.
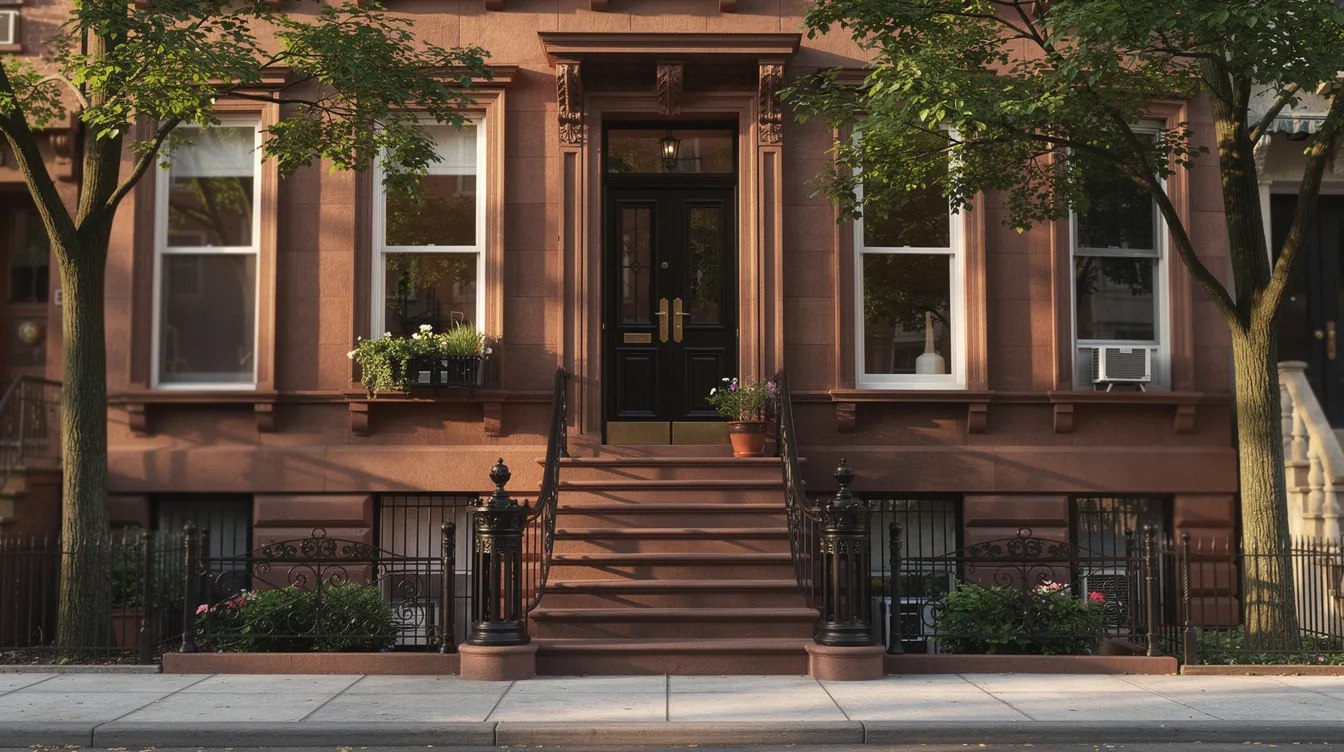
A step-by-step guide to inspections, renovation planning, and pricing a brownstone.
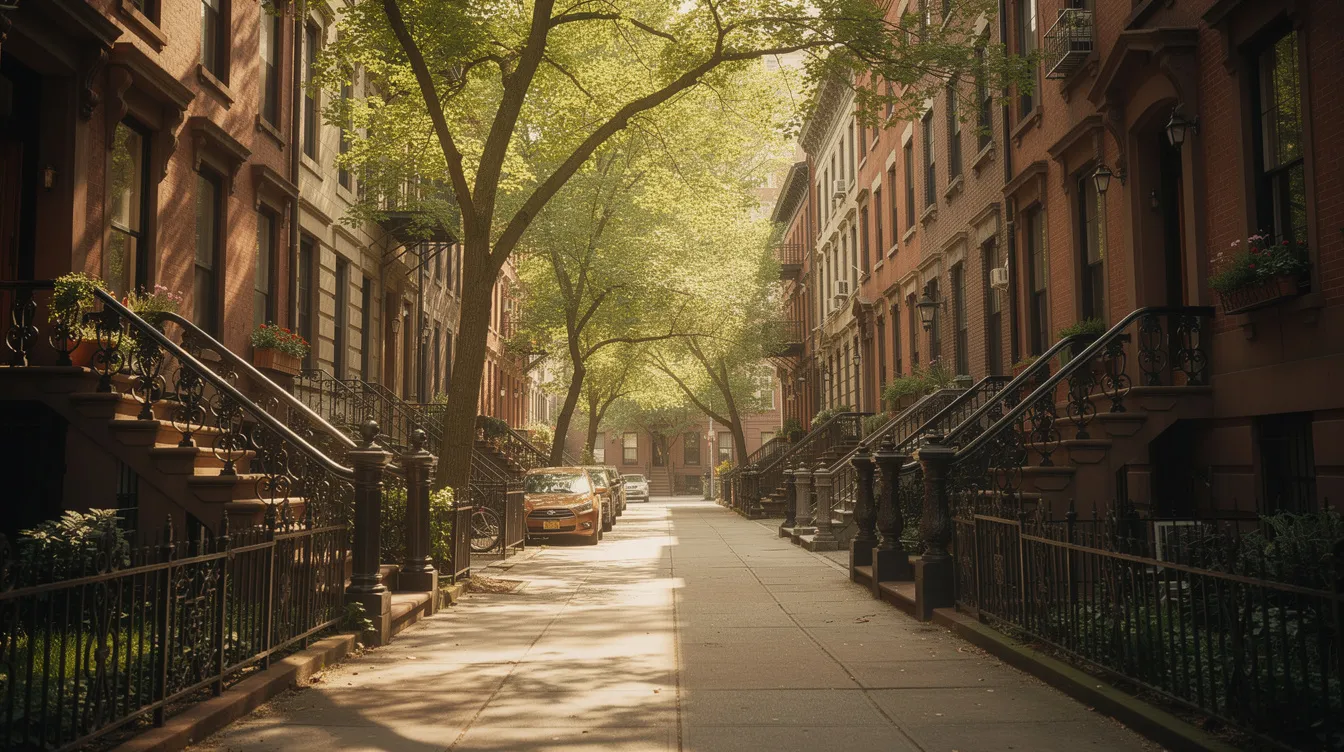
How brownstone financing works, from pre-approval to closing.
Reach out for buyer representation, listing strategy, or a confidential valuation with Stanley Montfort.